 FIXO
How to Maintain a Daily Production Register in a Small Factory
Quick answer: Maintain a daily production register by recording each batch or shift’s actual material consumption, accepted finished output, rejects, scrap and unfinished work. Link entries to material slips and stock records, get a supervisor to check unusual differences, and prepare monthly totals. Keep production separate from dispatches, and preserve the history of any corrections.
1. Understand what the register should show
A production register should answer three everyday questions: What material did we use? What did we make? Where did the remaining material go?
A useful entry connects the batch or job to its inputs, accepted output, unfinished work and losses. Recording only “450 pieces produced” leaves out the information needed to check consumption or explain scrap.
There is also an important distinction between a daily working record and a legal requirement:
- Section 35 of the CGST Act requires GST-registered businesses to maintain true and correct production/manufacturing and stock accounts. This is linked to registration, not a separate production-register turnover threshold.
- The general manufacturing requirement in Rule 56(12) of the CGST Rules is for monthly production accounts, including quantitative details of raw materials or services used, goods manufactured, waste and by-products.
- Daily entries are a practical way to build those monthly accounts—not a universal daily filing requirement.
The format below is an operational suggestion, not a prescribed form for every Indian factory. State- and product-specific requirements need checking for your business. The official consolidated documents reviewed are dated 2021; a complete sector-specific amendment check through 24 October 2026 has not been confirmed.
2. Set up a register that follows each batch or shift
Use a separate entry for each batch or shift, keeping different products clearly identifiable. If a batch uses several materials, give each material its own line rather than combining everything into one total.
| Field | What to record |
|---|---|
| Date and shift | When the work happened |
| Machine or production line | Where production took place |
| Product code and batch/job number | Which product and job the entry belongs to |
| Unit of measurement | kg, metres, litres or pieces, with documented conversions |
| Material details | Item-wise quantities issued, returned and actually consumed |
| Opening WIP | Unfinished quantities carried forward, identified by stage |
| Accepted output | Good finished goods transferred to stores |
| Other output | Rejects, rework, recoverable scrap, waste and by-products separately |
| Closing WIP | Unfinished quantities remaining, identified by stage |
| Supporting references | Issue slips, return slips, job cards, quality records and stock transfers |
| Review | Operator’s entry, supervisor’s check and explanations of unusual losses |
WIP means work-in-progress: material or goods that have entered production but are not yet accepted finished output.
Keep units consistent. Steel consumption measured in kilograms cannot be directly compared with brackets measured in pieces. Where both are needed, record the finished quantity in pieces and its corresponding weight, or document the conversion.
Do not force every output into a “good” or “bad” column. Rework, recoverable scrap and unrecoverable waste tell different stories and should remain distinguishable.
3. Follow the same routine every day
The register becomes useful when entries follow the movement of material, rather than being reconstructed at month end.
Before production, identify the job.
Enter the date, shift, machine or line, product and batch/job number. Carry forward opening WIP by stage so that unfinished work does not disappear between shifts.Record materials issued and returned.
Use numbered issue and return slips. Enter each material separately and record unused quantities sent back to stores. Material issued to the shop floor is not automatically material consumed.Record actual consumption.
Use the actual quantities for the batch or shift, keeping unfinished material visible in WIP. Do not simply copy standard consumption from the bill of materials. A standard quantity does not explain what happened during that day’s work.Count or weigh output at shift end.
Record accepted finished goods, rejects, items requiring rework, recoverable scrap, waste and by-products separately. Also record closing WIP by stage. Do not include unfinished or rejected goods in accepted production.Get a supervisor to review exceptions.
Check unusual consumption, losses and rework. Add an explanation alongside the entry and retain the relevant job card or quality reference. A recorded reason is more useful than an unexplained difference.Update the connected stock records.
Record accepted goods transferred to finished stores and keep dispatch entries separate. A batch may be produced today but dispatched later; one event should not stand in for the other.
At the handover, check that each entry has its supporting references. This connects the production total to the slips and counts behind it.
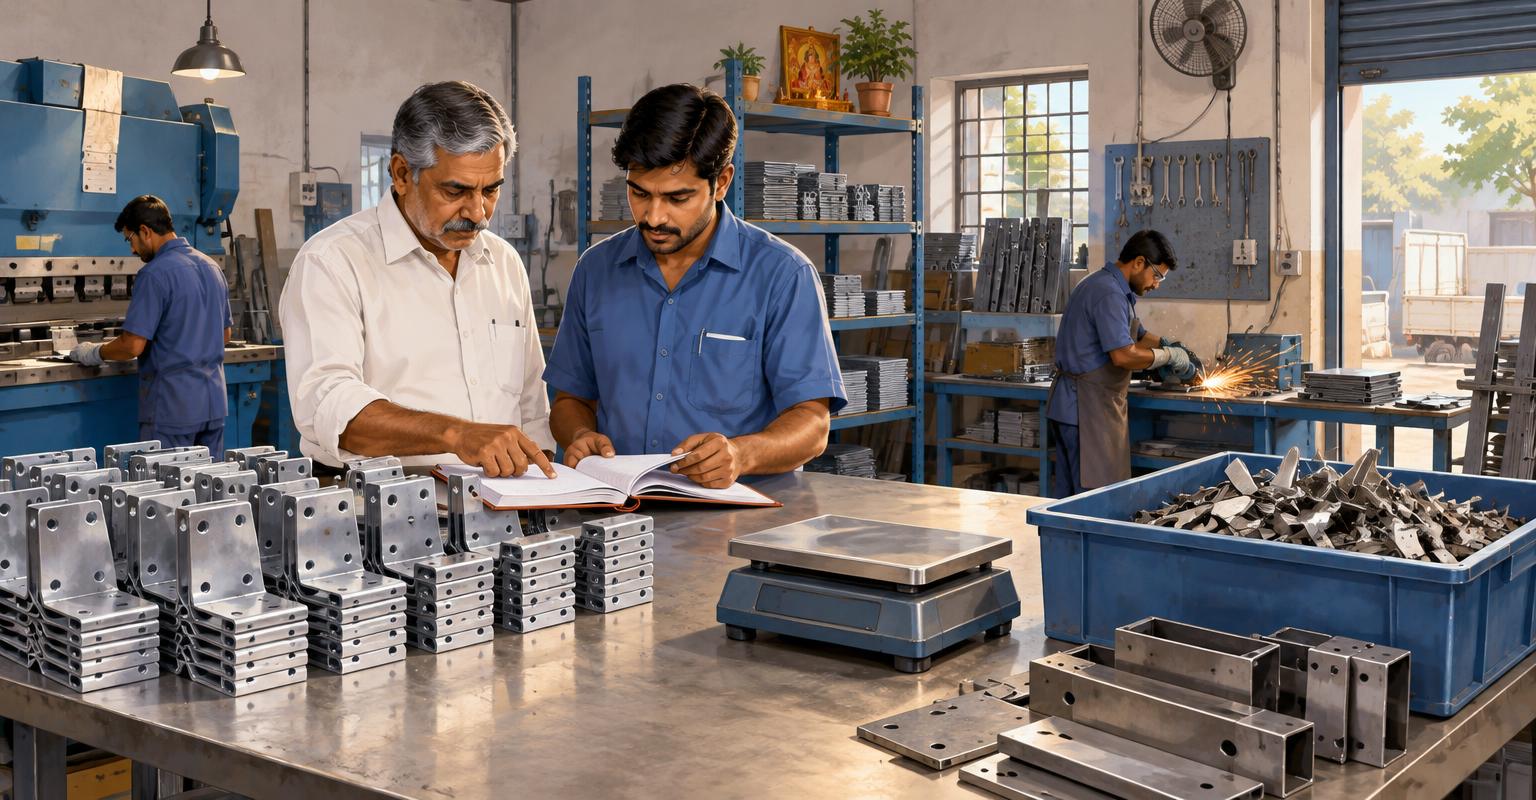
4. Example: One batch in a Pune sheet-metal workshop
Consider a workshop making steel brackets. The following quantities are illustrative, not industry-standard yields.
There is no opening or closing WIP for this batch.
| Batch item | Recorded quantity |
|---|---|
| Steel actually consumed | 100 kg |
| Accepted brackets | 450 pieces |
| Weight of accepted brackets | 90 kg |
| Recoverable offcuts | 8 kg |
| Unrecoverable process loss | 2 kg |
| Opening and closing WIP | Nil |
The material reconciliation is:
100 kg consumed = 90 kg accepted output + 8 kg recoverable offcuts + 2 kg process loss
The entry explains where the consumed steel went. Recording both the number and weight of accepted brackets also avoids comparing pieces directly with kilograms.
Now check finished-goods stock. Suppose the workshop had 100 accepted brackets in opening stock and dispatched 400 brackets. With no customer returns or other outward movements:
Closing stock = 100 opening + 450 accepted production − 400 dispatched = 150 brackets
Notice that production is 450 brackets, not 400. The dispatch figure tells you what left the factory, not what the factory made.
Record the 8 kg of recoverable offcuts separately in the scrap stock record. Scrap generated is not the same as scrap sold. If the offcuts remain at the workshop, they should not be treated as having left merely because production has ended.
The supervisor’s review should cover the recorded process loss and any unusual result, with supporting references retained against the batch.
5. Turn daily entries into a monthly production summary
At month end, summarise by item rather than adding together unrelated materials or products. A single combined total for kilograms, metres and pieces is not meaningful.
Use this sequence:
Total actual consumption by material.
Check that unused returns have been recorded and that issued quantities have not automatically been counted as consumed.Total accepted production by finished item.
Match the production register with the quantities transferred into finished-goods stock.Summarise other output separately.
Total rejects, rework, recoverable scrap, waste and by-products without merging them into accepted production.Check WIP carried forward.
Review opening and closing unfinished quantities by stage. Keep unfinished work visible rather than treating it as a finished-stock shortage.Reconcile finished stock and investigate differences.
For a simple finished-goods account, use:Closing stock = opening stock + accepted production + customer returns − dispatches − other documented outward movements
Compare the resulting records with physical counts and investigate differences. Do not silently adjust production merely to make the closing balance agree.
The monthly summary should be traceable back to daily entries and supporting slips. That connection makes it possible to examine a difference instead of guessing its cause.
6. Avoid the mistakes that make totals unreliable
Even a neat register can give misleading results if entries mix different activities.
- Recording sales as production: Keep manufacturing output separate from sales and dispatch movements.
- Counting unfinished goods as finished: Record closing WIP by stage and carry it forward.
- Counting rejected goods as accepted: Keep quality categories separate.
- Ignoring unused returns: Material sent back to stores should not remain recorded as consumed.
- Mixing kilograms and pieces: Document the conversion or record corresponding quantities in both units.
- Double-counting rework: Keep the rework movement identifiable so the same goods are not counted twice as accepted output.
- Copying standard consumption: Enter actual consumption rather than only the planned quantity.
- Changing old entries silently: Preserve the correction history.
A useful final check is: can someone follow the entry from the material slip through production to finished stock and scrap? If not, add the missing reference or explanation.
Frequently asked questions
Is a daily production register compulsory for every small factory?
The GST provisions reviewed require GST-registered businesses to maintain production and stock accounts, with monthly quantitative production accounts for manufacturing. Daily entries are a practical way to prepare those accounts, not a universal daily filing requirement. This suggested format should not be treated as complete compliance without checking the business’s state, product and registration details.
What should I record in a daily production register?
Record the date, shift, machine or line, product and batch number, and units of measurement. Include material issues, unused returns, actual consumption, opening and closing work-in-progress, accepted output, rejects, rework, scrap, waste and by-products. Add supporting slip references, the operator’s entry and a supervisor’s check, including explanations for unusual losses.
Can I maintain the production register in a spreadsheet?
A spreadsheet can organise daily entries, but an editable file alone should not be assumed to meet every GST recordkeeping requirement. The rules address edit and deletion history, backups and digital-signature authentication for electronic records. For paper registers, number each volume and preserve corrections by striking out errors under attestation rather than erasing or overwriting them.
How do I reconcile production with finished-goods stock?
For a simple finished-goods account, start with opening stock, add accepted production and customer returns, then subtract dispatches and other documented outward movements. Keep unfinished goods, rejects and scrap separate from accepted output. At month end, compare production totals with stock records and investigate differences found during physical counting.